
A complex playing field
An unpaid invoice is undoubtedly a nuisance. An unpaid invoice from abroad is not only a nuisance, but also complicated. When dealing with a Dutch customer, credit managers know the correct procedure: sending reminders, making telephone contact, possibly initiating a debt collection process and, ultimately, taking legal action. With a foreign debtor, the situation is more complex. A different language, different laws, different procedures and a different payment culture. It’s quite a challenge…
Limits on cross-border financing
As a Dutch company, you can generate turnover worldwide. But can you also finance your receivables globally? As your business grows internationally, the need for working capital often increases too. This is particularly true when foreign customers only pay after sixty, ninety or one hundred and twenty days. Of course, your suppliers, staff and tax bills still need to be paid. So your financing needs extend […]
Greater control in an unpredictable world
The OECD notes that the global economy will remain resilient in 2026, but that the outlook depends on future developments. The conflict in the Middle East, changing trade policies and export restrictions are creating additional uncertainty. Doing business internationally continues to offer opportunities, but it is also becoming more complex.
The world came together in Amsterdam
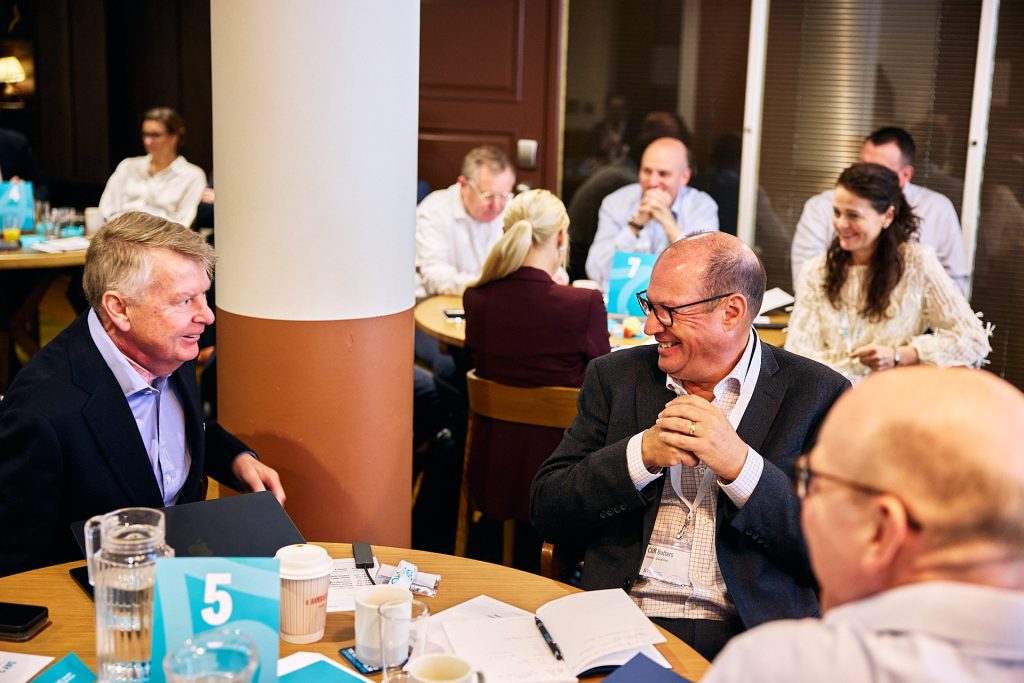
In early October, the partners of the ICBA (International Credit Broker Alliance) gathered in beautiful Amsterdam. Xolv was, of course, there! At a time when geopolitical developments and shifting trade flows are presenting the international business community with new challenges, cross-border collaboration is becoming increasingly important. The partners in the international ICBA network are specialist independent credit insurance brokers, operating collectively in around fifty countries. They are deeply rooted in local markets, businesses and credit risks. Handy!
Conquer those new markets!
Doing business internationally offers plenty of opportunities for growth, but it also entails risks. And, naturally, you’d prefer to win over new markets and customers without taking any unnecessary risks. That’s why you’ll naturally screen your potential partner in advance. The question is how thorough your screening is.
Protect, manage, free up
Your customers pay a certain number of days after you send your invoice. Your business costs continue to mount up. As your turnover grows – which is good news, of course – so does your accounts receivable portfolio. This automatically increases the amount you are effectively pre-financing, with the risk that a customer might pay late or not at all…
Do you provide financing for your customer?
If a customer only pays after ninety days, until then you are not just the supplier, but also the financier. You send an invoice; the turnover has been realised. But the money hasn’t come in yet. The later the customer pays, the longer your working capital is tied up. Now that interest and financing costs are rising again, this naturally makes an even greater difference.
A safety net or a growth accelerator?
Isn’t credit insurance simply a safety net against customers going bankrupt? That’s right. But it’s so much more than that. It’s a strategic tool for growing your business, entering new markets or, for example, offering more generous payment terms. You don’t just take out credit insurance for when your customer fails to pay. You take out credit insurance as a strategic tool to create commercial opportunities.
Higher interest rates, higher risk
Rising interest rates – the ECB raised rates by twenty-five basis points in June – have led to higher financing costs. On top of this come other cost increases, such as those for energy and staff. Customers with low margins or high levels of debt are the first to feel the impact. A customer who appears to be in a healthy financial position today may quickly find themselves with less financial headroom due to falling margins or declining demand.
Give all your customers some extra attention
Loyal customers often form the backbone of a business. They ensure continuity, predictable turnover and long-term business relationships. It is precisely for this reason that a sense of trust often develops, meaning that these customers’ payment behaviour is monitored less closely. This is understandable, but unfortunately it is not without risk.